AI venture debt is about to test a new kind of underwriting
Lenders face a familiar question in an unfamiliar market: how do you finance growth when the product is software but the cost base increasingly includes expensive and variable infrastructure?
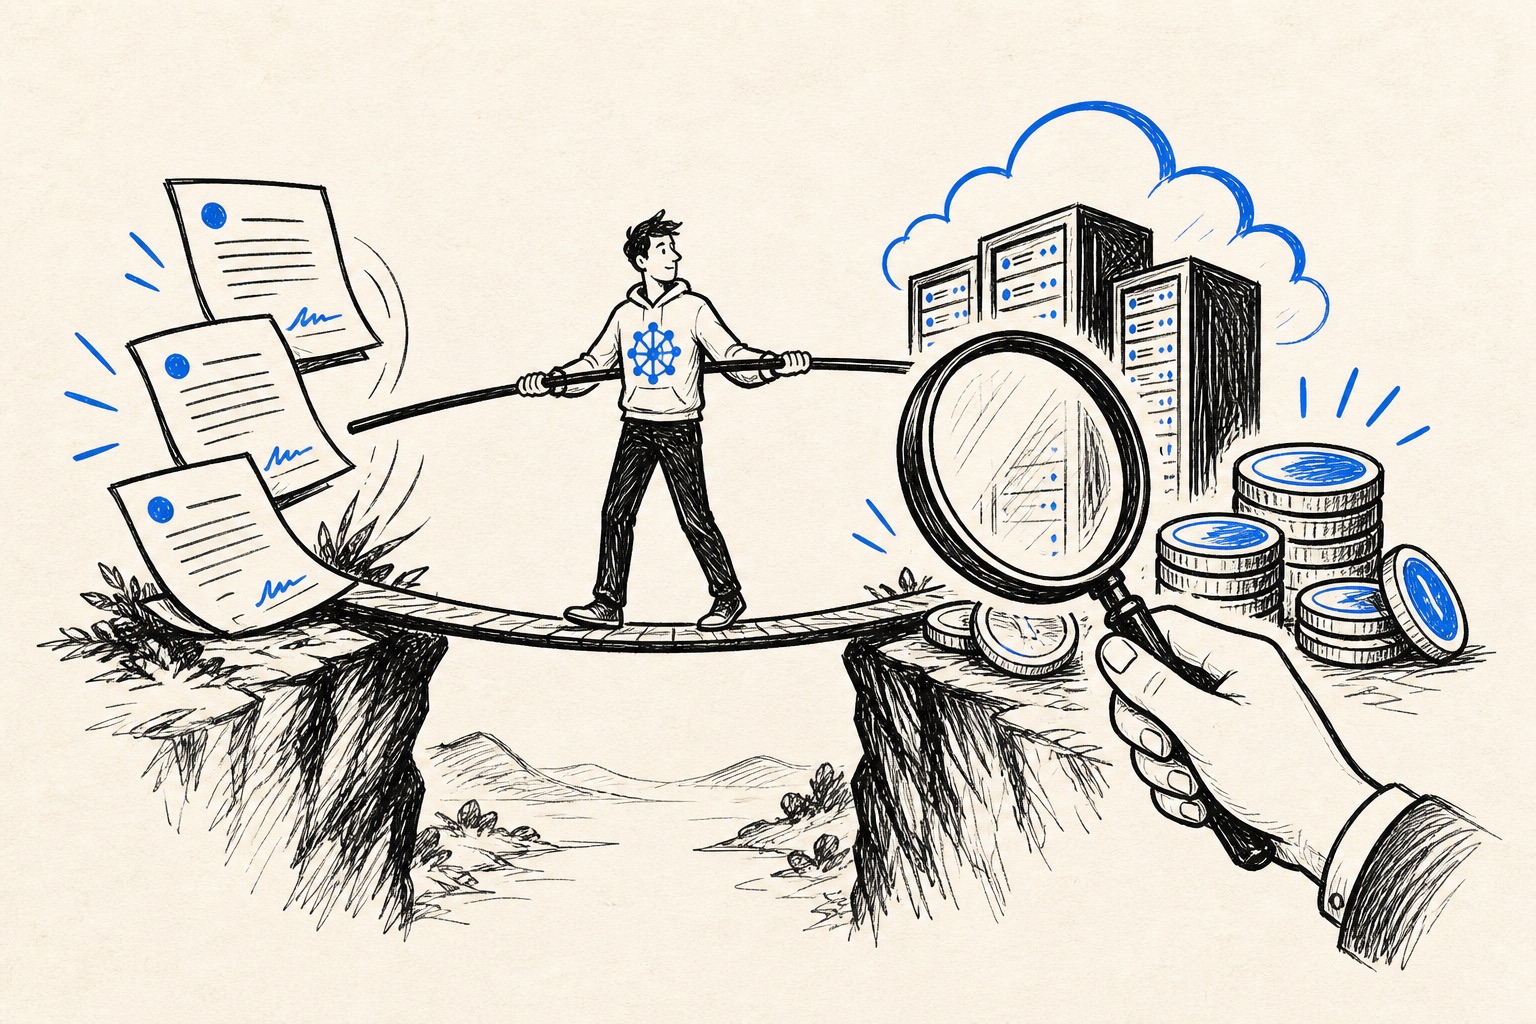
Venture debt has traditionally relied on a mix of sponsor quality, cash runway, recurring revenue and the expectation that a company can raise more equity if needed. AI companies complicate that pattern. Some look like software businesses to the customer, while carrying infrastructure costs and capital needs that behave very differently beneath the surface.
That does not make the sector unfinanceable. It means lenders need better ways to understand the relationship between revenue, model cost, customer concentration and the assets that actually support the service. The underwriting question is moving from growth alone to the quality of the operating model.
Recurring revenue can hide variable delivery cost
A subscription contract can create the appearance of familiar software economics, yet an AI provider may incur meaningful cost each time a customer uses the service. If the company has not designed strong pricing boundaries or efficient model routing, faster adoption can increase cash burn rather than improve operating leverage.
Lenders will need to look past contracted revenue to gross margin by customer and workload. A business with modest growth but a clear view of unit economics may be safer than one with impressive bookings and no reliable understanding of how much it costs to serve its most active accounts.
Infrastructure commitments can behave like hidden leverage
Reserved compute, long-term cloud commitments and specialized hardware agreements can be sensible ways to secure capacity. They can also create obligations that outlast a customer experiment. The risk is not simply that capacity is expensive. It is that the company has committed to a cost structure before proving that demand is durable enough to absorb it.
The best underwriting will distinguish flexible commitments from fixed ones, and productive capacity from capacity that exists mainly to support an optimistic forecast. A lender should understand what happens if usage grows slowly, a large customer leaves or model costs fall faster than the company’s contracts can adjust.
Customer concentration becomes more consequential
Concentration risk matters in every young software company, but it can be sharper when a handful of customers determine the pattern of an expensive infrastructure base. A single large account may justify a capacity build, then create a material revenue and utilization problem if its product strategy changes.
Lenders will want to know whether those customers are deeply integrated, whether contracts include meaningful commitments and how quickly the provider can redirect capacity. Diversification is not only about revenue. It is about creating enough different workloads that the company can adapt when one demand source softens.
The best borrowers will make their economics legible
AI companies that can explain their cost drivers clearly will have an advantage in financing conversations. That includes model mix, price controls, cloud commitments, customer retention and the operational plans that reduce delivery cost over time. A lender does not need perfect certainty. It needs a management team that understands the uncertainties it is carrying.
This is a moment for discipline rather than financial theater. The companies that treat capital as a bridge to a better operating model, rather than a substitute for one, will be better positioned when the market asks tougher questions about the quality of their growth.
AI finance will reward companies that know their true cost of service
Debt can be a useful tool for an AI business, but it will demand more than a familiar software narrative. The strongest borrowers will show how revenue, capacity and customer behavior connect, then build enough flexibility to withstand the moments when that connection changes.